
Financing a Partner Buyout Without Draining Cash Flow
Why finance a five-year build-out with money that demands repayment before the new location is fully open? Leasehold improvements can create a useful space. They can also absorb cash quickly. Commercial financing may help pay for construction, fixtures, technology, and other eligible project costs. The financing still needs to match the lease and the expected benefit period. Before borrowing, build the full renovation budget. Then test the monthly payment against the cash flow the location is likely to produce after opening. Commercial loan rates matter, but the project timeline matters too. Commercial business loans should be compared using the same build-out budget.
Build the Complete Renovation Budget
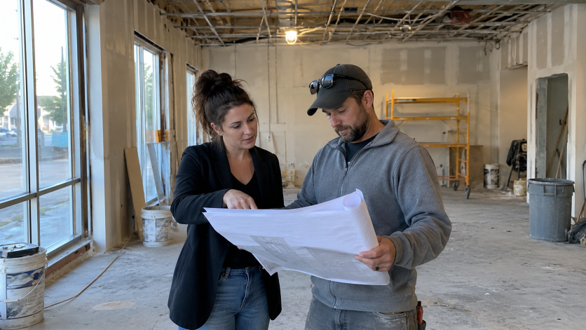
Start with the contractor estimate, but do not stop there. A build-out can include design fees, permits, inspections, fixtures, signage, technology, furniture, and utility work. The business may also lose sales during construction. Add moving and reopening costs when they apply. Keep a contingency for unexpected conditions behind walls or under floors. Then separate required work from optional upgrades. That helps if the project becomes more expensive. A clear budget also improves the financing discussion. The lender can see what the money will fund. The owner can see how much cash must be kept outside the project.
Review the lease before finalizing the construction plan. Some leases restrict signage, structural changes, or mechanical work. Others require landlord approval for contractors. A financing plan built before the lease is understood can fund improvements that are not allowed. The lease and the project budget should be reviewed together.
Ask the landlord to confirm approval requirements in writing. This reduces the risk of paying for plans that later need major changes.
Understand Landlord Contributions
Some leases include a tenant-improvement allowance. The landlord may pay or reimburse part of the build-out. Read the lease carefully. The allowance may only cover certain costs. It may also be paid after work is complete. That means the tenant could still need cash during construction. Ask when reimbursements occur and what documents are required. Also check whether unused allowance funds disappear. A landlord contribution can reduce the amount of commercial financing needed. It does not replace a cash-flow plan. The business still needs money for costs outside the allowance and for normal operations before the new space starts producing revenue.
Timing matters because rent may start before the business opens. Free-rent periods can help, but they eventually end. Add rent during construction to the cash-flow model if it applies. Also consider delays in permits or inspections. The business should not depend on an exact opening date to make the financing work.
Build permit delays into the schedule. One extra month of rent and payroll can matter more than a small construction change order.
Match the Financing Term to the Benefit Period
The improvements only create value while the business can use the space. Compare the loan term with the remaining lease term and renewal options. Also consider the useful life of the improvements. A long loan may lower the monthly payment, but it can outlast the lease. A short loan may create a payment that is too high during ramp-up. Use a commercial loan calculator to test several terms and rates. Then add the payment to the location’s projected cash flow. The right term should balance affordability with the period the improvements are expected to benefit the business. Use a commercial loan calculator with more than one rate and term. This makes commercial loan rates easier to compare.
Use the calculator for more than one case. Test a base budget, a 10% overrun, and a delayed opening. Then compare the monthly payment with projected sales. This shows whether the company has enough cushion. A project that only works at the original budget may be too fragile for normal construction risk.
A calculator is most useful when the inputs are realistic. Use a range of rates and project costs, not one perfect estimate.
Plan for Overruns Before Construction Starts
Most projects change. A permit can take longer. Materials can cost more. Electrical work may expand. Set a contingency before construction begins. Also decide which upgrades can be delayed if costs rise. Keep a list of must-have items and nice-to-have items. This prevents last-minute borrowing at expensive terms. Update the budget whenever a change order is approved. Do not wait until the project is nearly finished. A small overrun can be manageable. Several untracked overruns can create a working-capital problem before the doors open.
Keep change orders controlled. Every change should show the added cost and any effect on timing. Small upgrades can feel harmless during construction. Together, they can consume the contingency. Require a simple approval process even for owner-requested changes. This keeps the project aligned with the financing plan.
Require every change order to show both cost and timing. A cheaper change can still be expensive if it delays opening by several weeks.
How Money Man 4 Business Helps Compare Commercial Financing Structures
Money Man 4 Business can help owners compare commercial financing with the lease economics in mind. MM4B can review project cost, monthly payments, lease term, and post-opening cash flow. Clients may work with a CFO with 34+ years of experience. That can help when the build-out competes with payroll, inventory, and other expansion costs. The right structure may be a term loan, SBA option, or another commercial program, subject to eligibility and underwriting. The aim is to finish the space without leaving the business short on operating cash. Commercial business loans can differ in fees, collateral, and repayment flexibility. Commercial financing should be tested against the opening schedule.
After opening, track whether the improvements produce the expected benefit. Better layout may increase capacity. New fixtures may improve customer experience. Technology may reduce labor. Compare actual results with the original case. That information helps the owner judge whether future renovations should use similar financing or a different approach.
Measure results after opening. If the improvements do not create the expected benefit, that lesson should shape the next expansion project.
Before signing the financing, compare the build-out budget with the lease calendar. Mark rent commencement, expected opening, contractor milestones, and loan payments on one timeline. This shows where cash pressure may overlap. It also makes delays easier to price before they happen, which is useful when deciding how much contingency to keep. Share the timeline with the contractor and finance team. A common schedule makes it easier to spot when a construction delay will create an extra month of rent, payroll, or loan costs.
Frequently Asked Questions
Can a business loan finance tenant improvements?
Yes, depending on the lender, loan program, lease, and project. The lender will need to confirm which costs are eligible.
Should the loan term be longer than the lease?
That can create risk. The financing term should be considered alongside the lease term, renewal options, and useful life of the improvements.
How much contingency should a build-out budget include?
There is no universal amount. The right cushion depends on project complexity, contractor pricing, and how much uncertainty remains.
Build the Space Without Emptying the Operating Account
A renovation should help the business earn more, serve customers better, or support growth. It should not create a cash shortage before opening. Build the full project budget, understand landlord contributions, and test several payment structures. Money Man 4 Business can help owners compare commercial financing and monthly cash-flow effects. The right plan pays for the space while leaving enough cash to operate inside it. A commercial loan calculator is most useful when the budget includes overruns and delays.
💡 Ready to grow your business?
Explore your funding options with Money Man 4 Business. We specialize in working capital and consolidation in different USA states and cities. Check our State wise Small Business Loan Insights