
Business Term Loans vs. Merchant Cash Advances
How much of your business income are you losing to high-interest financing? If this number makes you nervous, maybe it’s time to take a look at your terms. A small business term loan and Merchant cash advance both can add working capital to your business. However, term loans are structured as a principal and interest payment, whereas an advance is a single lump sum paid back over time. For owners who think about inventory and bills each and every day, it is not important how long your loan application takes. It is more important to know how much money will be left to your business after the payment.
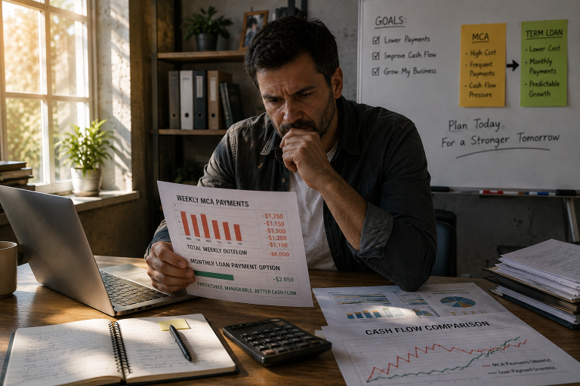
When Fast Money Starts Controlling the Week
Funding that keeps pace with the speed of your business is critical when time is of the essence. A malfunctioning machine, a profitable buying opportunity, an outstanding receivable, or a costly surprise repair will not wait for a standard financing process. Because of this, MCA funding is often sought after. Funding decisions may rely heavily on recent deposits and income, and the funding process can start rapidly.
MCA funding appears to be a solution to your funding needs, but the products can erode cash rapidly. Many MCA funding agreements will cannibalize incoming cash by requiring daily or weekly withdrawals from a business checking account until the receivables have been collected. A business can appear to be profitable, but still run out of cash because withdrawals are greater than payments owed to staff and to outside vendors. One withdrawal can seem to be within reasonable constraints, but multiple withdrawals or funding back to back can lead to a cash flow crisis.
MCA funding can solve a business need for fast funding, but the high cost of funding can quickly eat up your profit.
What a Term Loan Changes
A business term loan lets a borrower know how much he or she can borrow over a given period to repay the loan. As most programs maintain a schedule of monthly payments, the borrower is aware of payment due dates. More important than pricing is control. A business owner can plan the cash flow of the business and compare the financing cost he or she will incur against the benefit of the cash flow.
The financing term is critical for the use of capital to buy equipment or inventory, renovate facilities, or expand a business. If the asset increases value over several years, financing the term of the asset over a longer period can be useful to keep the cash outflow limited.
Money Man 4 Business offers access to term loans between 1 and 25 years of financing, subject to underwriting and program availability. It gives more time between expected loan payments for the business owner than the daily or weekly collections.
Could Consolidation Be the Better Question?
Some owners already have multiple debt obligations when they reach the point of making the financing decision. Those can be a combination of MCAs, short-term ACH loans, credit card debt, and other high-cost debt. Taking another advance can result in an already busy week becoming busier with yet another obligation.
A more informative question is whether some or all of those debt obligations can be replaced with a longer-term, lower-payment consolidation. Money Man 4 Business advocates for MCA and other debt consolidations as a primary purpose of certain longer-term options. Higher cash flow is the goal of this approach.
Money Man 4 Business also states that a significant portion of consolidations that qualify substantially lower the interest and fees. In fact, savings of 2/3 or more are common when replacing high-cost debt with longer-term financing. The savings realized depend on the exact terms of the financing as well as fees. Therefore, all that matters is the comparison of actual savings to actual debt and financing, not the promotional wording.
Compare the Real Cost, Not Just the Quote
A term loan and a Merchant cash advance (MCA) have different features and should not be used interchangeably. A term loan has a stated interest rate, true APR where available, payment amount, and term. An MCA has a factor, a purchased amount, and a total payback amount. The factor should not be interpreted the same way as an APR.
Prior to agreeing to either of these, see what the net cash received will be, the total amount that will be repaid or provided, the payment frequency, the fees, the expected time to pay off the advance, the terms to pay off the advance, and what will happen if sales drop. After this, adjust the payment amount to see how it will impact your cash flow.
According to the Small Business Credit Survey conducted by the Federal Reserve Banks in 2026, 60% of employer firms applied for financing in the 12 months leading up to the survey, and 56% of applicants sought financing to meet operating expenses. This serves as a clear reminder that much financing is used for day-to-day operating needs. Any financing structure that will recreate the issue of cash flow should be carefully looked at.
How Money Man 4 Business Approaches the Problem
Money Man 4 Business has a unique approach for applicants. It does the legwork to match potential borrowers with the right business loan programs based on the reason for borrowing, the existing debt burden, and the cash flow. Money Man 4 Business’s long-term products are structured around business loans with monthly payments, with published programs that incorporate options for working capital, equipment financing, SBA financing, and MCA or debt-refinancing.
The company also provides CFO-level advisory support. Money Man 4 Business states that business owners work with a Chief Financial Officer who has 34+ years of helping business owners analyze financing and cash flow. This is important because a business that has multiple obligations may not just need another approval. Such a business may need someone to review the entire situation and determine what financing should be refinanced, what should remain unchanged, and what payment the business can afford.
Which Option Fits a Growing Business?
A Merchant cash advance is best when speed is required, and the cost vs return is clear. If a company’s owner understands that one cash advance means they will have to make several in return to collect, then cash advances are probably appropriate. The problem occurs when funds are withdrawn regularly, leaving the company without the cash to run their operation.
A business term loan makes sense when the company knows the purpose for the capital, and needs time for it to generate a return on the company’s investment. Businesses should look into this when they have multiple significant financial obligations that make it difficult for them to manage.
The best way to determine what kind of financing makes the most sense is to determine if the company can continue to pay staff, suppliers, and cover its obligations after a loan payment is made. If the financing doesn’t make that determination, then the financing amount, term, and especially the product need to change.
Frequently Asked Questions
Is an MCA the same as a business loan?
Generally, they are not the same. An MCA is commonly structured as a purchase of future receivables or revenue, while a term loan is debt repaid under a loan agreement. Legal treatment can vary by product and jurisdiction.
Are monthly payments always cheaper?
Not necessarily. Payment frequency and total cost are different issues. Monthly payments may be easier to budget, but owners still need to compare APR or annualized cost, fees, term length, and total payback.
Can existing MCAs be consolidated?
Yes, in some cases. Eligibility depends on the business, existing obligations, credit profile, revenue, and the refinancing program. Money Man 4 Business offers programs that may be used for MCA and other debt refinancing.
Choose Financing That Gives the Business Room to Breathe
Financing should help improve cash flow, not build cash flow hurdles. Compare the benefits of a business term loan to the costs of an MCA. Focus on the future costs of each funding option and how cash flow will be post-funding.
Money Man 4 Business offers credit programs, cash flow consolidation, and long term flexible payment options spanning 1-25 years. While weekly or daily cash advances may be necessary to fulfill obligations, consider if additional cash advances are the best alternative to your current obligation structure.
💡 Ready to grow your business?
Explore your funding options with Money Man 4 Business. We specialize in working capital and consolidation in different USA states and cities. Check our State wise Small Business Loan Insights