
Home-Service Company Financing: HVAC, Plumbing, and Electrical Growth Without Cash-Flow Strain
Home-service businesses grow through people, vehicles, tools, and speed. An HVAC, plumbing, or electrical company may need to add vans, stock more parts, hire technicians, and market aggressively before the extra revenue fully arrives. That is why many owners start looking at small business funding during growth periods. The right financing can help a company expand capacity. The wrong financing can strain cash so badly that growth becomes harder to manage than staying small.
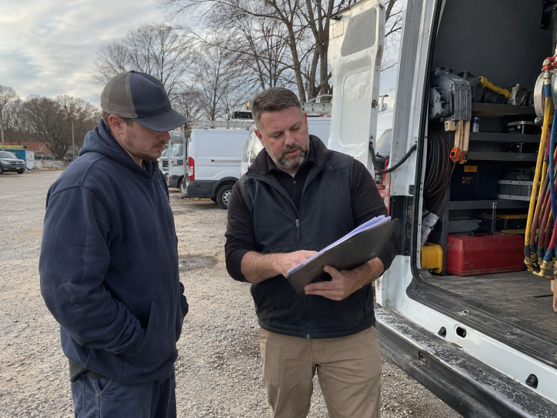
Why fast-growing service companies feel short on cash
Service companies often collect faster than some other industries, but growth still costs money upfront. A new van must be outfitted. A technician must be paid before that person reaches full billable productivity. Inventory has to be available for urgent jobs. Marketing has to run before new calls come in. Growth looks positive from the outside, yet inside the company it can create a temporary but very real cash squeeze.
That is why financing should reflect how the company actually operates. Many owners prefer a fixed monthly payment business loan because predictable repayment is easier to budget around payroll, fuel, and service-call volume. The payment should support growth, not interrupt dispatch decisions every week.
What the money is usually used for
In home services, borrowed funds often go toward service vans, ladders, testing equipment, inventory, software, recruiting, and working capital for payroll. Some companies also refinance older obligations into one cleaner structure. Each use has a different time horizon. A van may generate revenue for years. Seasonal payroll support may only be needed for a few months. The owner should match the repayment term to the life of the need.
When the main need is trucks, tools, or specialized gear, equipment financing monthly payments for small business may be a better fit because it ties repayment to a defined business asset. When the main need is broader expansion, a working-capital or term structure may be more useful. The business should know whether it is buying equipment, building capacity, or simply bridging a short cash gap.
How growth can go wrong
One mistake is adding too much capacity before call volume is stable enough to support it. Another is assuming every new technician will become fully productive immediately. Training time, callbacks, and route inefficiencies can reduce near-term cash even when long-term growth still makes sense. Good financing planning leaves room for that learning curve.
Another mistake is accepting the first fast offer without testing the payment against slower months. A company comparing business term loan monthly payments should look at winter and shoulder-season revenue, not only peak summer demand. If the payment only works in the strongest months, the structure may be too aggressive.
How to decide the right amount
A simple plan starts with the next twelve months. Estimate current revenue, likely service demand, technician capacity, and the cost of each new hire or van. Then separate essential spending from optional growth spending. This shows what the company truly needs now and what can wait until later. Borrowing in stages is sometimes safer than taking one larger amount based on an optimistic forecast.
This is where small business funding should be treated as part of a growth plan, not a shortcut around planning. The company should know how each dollar is expected to support more calls, better service, or stronger cash flow. If that link is unclear, the amount is probably too high or the timing is too early.
Why predictable payments matter
Home-service operations move quickly. Calls come in all day. Dispatch decisions are constant. Owners cannot spend every week wondering how much cash a funding product will pull next. Predictable repayment makes it easier to manage payroll, parts buying, and daily operations. It also helps when the business wants to expand again later because records are cleaner and cash behavior is easier to explain.
That is why many growing companies review a fixed monthly payment business loan or a clearly structured equipment option instead of choosing repayment that changes too often. Predictability does not remove the need for planning, but it makes planning possible.
How Money Man 4 Business helps home-service owners
Money Man 4 Business helps home-service companies compare financing through a practical operating lens. Owners can review payment size, total cost, use of funds, and how a structure fits vans, technicians, marketing, and working capital. The discussion is not only about approval. It is about whether the company can still operate comfortably after funding lands.
With more than 34 years of experience and CFO-level guidance, Money Man 4 Business helps owners compare business term loan monthly payments, equipment options, and other solutions more clearly. That helps an HVAC, plumbing, or electrical company grow without loading cash flow with the wrong kind of debt.
Plan the return on each borrowed dollar
When the plan is clear, small business funding becomes easier to monitor after closing. Management can review whether the money increased call capacity, improved gross margin, or simply covered a temporary gap. That feedback also makes future borrowing decisions better because the company learns which type of financing actually supported growth.
It also helps to gather service-call volume, maintenance memberships, seasonal peaks, and technician productivity before applying. Owners considering a fixed monthly payment business loan should know whether the company can still carry the payment in shoulder months, not only during its busiest weeks. That discipline keeps growth grounded in real demand rather than enthusiasm alone.
A growing service company should ask what each borrowed dollar is meant to produce. Will a new van allow two more technicians to stay billable? Will added inventory reduce return visits? Will recruiting spend shorten lost-revenue gaps from open positions? That analysis is useful when comparing equipment financing monthly payments for small business because it ties the payment to a practical operating benefit instead of a vague growth goal.
Owners should also look at gross profit by service line before expanding. Some calls may produce strong revenue but weak margin once travel time, parts, warranty work, and technician hours are included. A company using small business funding for growth should know which services actually create enough cash to support the added payment.
The same rule applies to hiring. A new technician may need weeks of training, ride-alongs, and supervision before reaching a full schedule. The financing plan should include that ramp-up period. If the business is considering a fixed monthly payment business loan, the payment should remain comfortable while the new employee is still building productivity, not only after the schedule is full.
A final check is the service backlog. If demand already exceeds technician capacity, added vehicles and hiring may make sense. If the schedule is inconsistent, the company may need better lead generation first. Financing should follow proven demand. Owners comparing business term loan monthly payments should connect the payment to a realistic increase in completed jobs, not only to the hope that growth will appear after the money arrives.
Frequently Asked Questions
What type of financing is often used for vans and tools? Equipment-focused financing is often used because the purchase is tied to a business asset.
Why do home-service companies value fixed payments? Because predictable payments are easier to manage around dispatch, payroll, and seasonal demand.
Should a company borrow for growth all at once? Not always. Borrowing in stages can reduce risk and make growth easier to track.
Final Thought
Good home-service financing supports capacity without overwhelming cash flow. Match the amount to the real growth plan, keep payments predictable, and leave room for slower months.
💡 Ready to grow your business?
Explore your funding options with Money Man 4 Business. We specialize in working capital and consolidation in different USA states and cities. Check our State wise Small Business Loan Insights