
SBA 7(a) Loans vs. MCA Funding for Small Business
Is fast cash really a win when payment starts eating into your cash flow before the new investment starts making money? This question is important when an owner is considering an sba 7(a) loan versus an application for MCA funding. Both can fund a business, but they’re meant for different things. One focuses on longer-term, structured payback. The other focuses on faster payback with recent business revenue. The decision depends on the purpose of the money, the timing of the need, and what the business can afford as a payback for the funds.
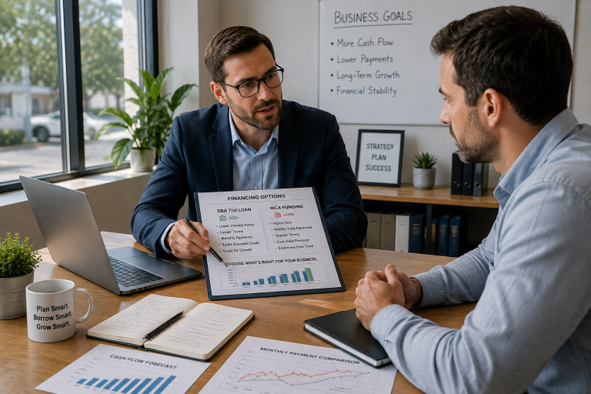
Why Fast Funding Is So Tempting
There are times when an owner has no other choice than to resort to quick business funding. The deadline for payroll is approaching. A critical piece of machinery suddenly breaks. A supplier has a limited time offer on Friday. A client delays a large payment. That is when the owner is left with no other choice than to use Fast business funding.
It is understandable to see the appeal for owners in this position to do a merchant cash advance. The advance is typically based on a company’s sales amount and can be approved in less time than a traditional bank loan. The speed cash advance option is also attractive to anyone who has been turned away from traditional financing.
The problem owners are faced with is what happens after the advance is approved. If the funding requires daily or weekly collections, it could potentially create a cash flow problem after the funding period is over.
What an SBA 7(a) Loan Is Designed to Do
The SBA 7(a) Program is the Small Business Administration’s (SBA) primary loan program. The SBA does not provide borrowed funds directly. Lenders that participate in the program make qualifying loans and receive an SBA guarantee which provides the lender a portion of the risk.
The sba 7(a) loan can be used for several purposes, such as working capital, purchasing, furniture, fixture, supplies, real estate, business acquisition, and certain forms of debt refinancing. The maximum individual 7(a) loan is $5 million. The actual approval amount will depend on the lender, the borrower’s ability to repay, and the details of the transaction and the program’s eligibility.
One of the biggest practical differences is the structure of the loan repayment. Most terms 7(a) loans are structured to have the principal and interest drawn from the cash flow of the business, and are paid monthly.owners that have a monthly budget, the model of sba loan monthly payments along with budget items, such as rent, payroll, taxes, insurance, and the other fixed expenses of the business, is a relatively easy structure to budget for the business.
Speed vs. Sustainability
SBA financing requires more information from applicants because lenders need to see that the business can handle the debt. Examples of information required are tax returns, projections, financial statements, debt schedules, ownership information, and plans for how the funds will be used. This is more involved than many fast funding forms.
However, the length of the form does not negatively impact the process. In some cases, the forms actually encourage the applicant(s) to reflect on the business decision. For example, the focus should not be on the time it takes to receive the funds, but whether the business can support the cost of the financing.
Evaluating the trade-off of the pros and cons of speed is still important. Business owners are usually interested in funding that meets their needs quickly, and for a variety of reasons, evaluating the pros and cons of speed is important. The most affordable funding that is the fastest also only makes sense economically during an emergency.
Just because an application process is fast does not mean owners should rush to Apply for MCA financing. There are several key terms to consider, including total cost of the financing, true APR or annualized cost where available, payment frequency, and how long funds are collected prior to payment during slow sales.
What If the Business Already Has Expensive Debt?
This is where the conversation usually changes. The owner is not starting from zero. There could be two MCAs, credit card debt, equipment debt, or a short-term loan already in the background. Fast business funding on top of these obligations could give cash today, but definitely make tomorrow’s payment harder.
Refinancing and consolidating debt can be done using some SBA and longer-term financing programs. These should not be used for moving debt to a more convenient location. The point is to have better structure with fewer payments, longer payment terms, and more predictable and consistent monthly cash flow.
Money Man 4 Business focuses on consolidation and refinancing solutions for businesses. The company says qualifying restructures can lead to a significant reduction in interest costs and fees, often to the tune of two-thirds or more of the total cost and fees of high-cost eligible debt. The actual results depend on underwriting and the debt being replaced, but it is worthwhile to do the math to check the savings before accepting a refinance.
How Money Man 4 Business Helps Owners Compare the Options
An application for financing should not start with the question, “Which product can approve me fastest?” The correct starting question should be, “What problem am I actually trying to solve?” Money Man 4 Business offers access to several types of financing options, including SBA loans, longer-term working capital loans, lines of credit, and term refinancing. Money Man 4 Business offers term loans that can extend from 1-25 years, pending the program and qualification, and provides cash flow management through a monthly payment structure.
The company also provides direct financial guidance. Money Man 4 Business states that their clients receive financial guidance from a CFO with over 34 years of experience, helping business owners evaluate financing. For an owner with multiple debts, that kind of review is useful to help determine if the best answer is new financing, consolidation, refinancing, or a smaller financing amount.
When an SBA Loan May Make More Sense
An SBA-backed loan is best for planned, long-term requirements, like purchasing equipment, buying a business, expanding a location, refinancing eligible debt, or creating a larger working capital cushion. Longer-term financing allows for the value appreciation of the financed asset before the debt is completely amortized.
An MCA may be considered for an urgent, short-term financing need with a clear potential return, but its cost and collection timeline should be understood first. Because MCAs can be high-cost and may collect daily or weekly, they should be compared carefully with longer-term options. Neither should an sba 7(a) loan be thought of automatically as affordable. The numbers still have to work out.
The right solution to financing is the one that meets the financing requirement without keeping the operating account strained.
Frequently Asked Questions
How much can an SBA 7(a) loan provide?
The SBA states that the maximum individual 7(a) loan amount is $5 million. Actual approval depends on eligibility, lender underwriting, the purpose of the financing, and repayment ability.
Does SBA require one universal minimum credit score?
No single minimum score applies to every 7(a) loan. Lenders apply underwriting standards within SBA program requirements.
Is an MCA always faster?
MCAs are commonly marketed for speed, but timing varies by provider and file. SBA financing generally requires more documentation and underwriting, so it often takes longer.
Look Beyond the Funding Date
One day is all you need to receive financing, but the impact of financing decisions can last a lifetime for your business. Compare the length of money inflow from an SBA loan against the money inflow from Fast business funding. Consider which structure will allow you to maintain operational cash flow for an average and a challenging month.
Money Man 4 Business provides tools to anybody wanting to compare SBA financing and other term programs to refinance debt and consolidate existing financing. If the business has an expensive, short-term debt, look into a longer-term debt refinance. It may be more beneficial than a new financing advance. The goal of any financing should be to maintain, and even improve, the cash flow of your business.
💡 Ready to grow your business?
Explore your funding options with Money Man 4 Business. We specialize in working capital and consolidation in different USA states and cities. Check our State wise Small Business Loan Insights