All posts in Small business

Home-Service Company Financing: HVAC, Plumbing, and Electrical Growth Without Cash-Flow Strain

Home-service businesses grow through people, vehicles, tools, and speed. An HVAC, plumbing, or electrical company may need to add vans, stock more parts, hire technicians, and market aggressively before the extra revenue fully arrives. That is why many owners start looking at small business funding during growth periods. The right financing can help a company expand capacity. The wrong financing can strain cash so badly that growth becomes harder to manage than staying small.


Why fast-growing service companies feel short on cash

Service companies often collect faster than some other industries, but growth still costs money upfront. A new van must be outfitted. A technician must be paid before that person reaches full billable productivity. Inventory has to be available for urgent jobs. Marketing has to run before new calls come in. Growth looks positive from the outside, yet inside the company it can create a temporary but very real cash squeeze.

That is why financing should reflect how the company actually operates. Many owners prefer a fixed monthly payment business loan because predictable repayment is easier to budget around payroll, fuel, and service-call volume. The payment should support growth, not interrupt dispatch decisions every week.

What the money is usually used for

In home services, borrowed funds often go toward service vans, ladders, testing equipment, inventory, software, recruiting, and working capital for payroll. Some companies also refinance older obligations into one cleaner structure. Each use has a different time horizon. A van may generate revenue for years. Seasonal payroll support may only be needed for a few months. The owner should match the repayment term to the life of the need.

When the main need is trucks, tools, or specialized gear, equipment financing monthly payments for small business may be a better fit because it ties repayment to a defined business asset. When the main need is broader expansion, a working-capital or term structure may be more useful. The business should know whether it is buying equipment, building capacity, or simply bridging a short cash gap.

How growth can go wrong

One mistake is adding too much capacity before call volume is stable enough to support it. Another is assuming every new technician will become fully productive immediately. Training time, callbacks, and route inefficiencies can reduce near-term cash even when long-term growth still makes sense. Good financing planning leaves room for that learning curve.

Another mistake is accepting the first fast offer without testing the payment against slower months. A company comparing business term loan monthly payments should look at winter and shoulder-season revenue, not only peak summer demand. If the payment only works in the strongest months, the structure may be too aggressive.

How to decide the right amount

A simple plan starts with the next twelve months. Estimate current revenue, likely service demand, technician capacity, and the cost of each new hire or van. Then separate essential spending from optional growth spending. This shows what the company truly needs now and what can wait until later. Borrowing in stages is sometimes safer than taking one larger amount based on an optimistic forecast.

This is where small business funding should be treated as part of a growth plan, not a shortcut around planning. The company should know how each dollar is expected to support more calls, better service, or stronger cash flow. If that link is unclear, the amount is probably too high or the timing is too early.

Why predictable payments matter

Home-service operations move quickly. Calls come in all day. Dispatch decisions are constant. Owners cannot spend every week wondering how much cash a funding product will pull next. Predictable repayment makes it easier to manage payroll, parts buying, and daily operations. It also helps when the business wants to expand again later because records are cleaner and cash behavior is easier to explain.

That is why many growing companies review a fixed monthly payment business loan or a clearly structured equipment option instead of choosing repayment that changes too often. Predictability does not remove the need for planning, but it makes planning possible.


How Money Man 4 Business helps home-service owners

Money Man 4 Business helps home-service companies compare financing through a practical operating lens. Owners can review payment size, total cost, use of funds, and how a structure fits vans, technicians, marketing, and working capital. The discussion is not only about approval. It is about whether the company can still operate comfortably after funding lands.

With more than 34 years of experience and CFO-level guidance, Money Man 4 Business helps owners compare business term loan monthly payments, equipment options, and other solutions more clearly. That helps an HVAC, plumbing, or electrical company grow without loading cash flow with the wrong kind of debt.

Plan the return on each borrowed dollar

When the plan is clear, small business funding becomes easier to monitor after closing. Management can review whether the money increased call capacity, improved gross margin, or simply covered a temporary gap. That feedback also makes future borrowing decisions better because the company learns which type of financing actually supported growth.

It also helps to gather service-call volume, maintenance memberships, seasonal peaks, and technician productivity before applying. Owners considering a fixed monthly payment business loan should know whether the company can still carry the payment in shoulder months, not only during its busiest weeks. That discipline keeps growth grounded in real demand rather than enthusiasm alone.

A growing service company should ask what each borrowed dollar is meant to produce. Will a new van allow two more technicians to stay billable? Will added inventory reduce return visits? Will recruiting spend shorten lost-revenue gaps from open positions? That analysis is useful when comparing equipment financing monthly payments for small business because it ties the payment to a practical operating benefit instead of a vague growth goal.

Owners should also look at gross profit by service line before expanding. Some calls may produce strong revenue but weak margin once travel time, parts, warranty work, and technician hours are included. A company using small business funding for growth should know which services actually create enough cash to support the added payment.

The same rule applies to hiring. A new technician may need weeks of training, ride-alongs, and supervision before reaching a full schedule. The financing plan should include that ramp-up period. If the business is considering a fixed monthly payment business loan, the payment should remain comfortable while the new employee is still building productivity, not only after the schedule is full.

A final check is the service backlog. If demand already exceeds technician capacity, added vehicles and hiring may make sense. If the schedule is inconsistent, the company may need better lead generation first. Financing should follow proven demand. Owners comparing business term loan monthly payments should connect the payment to a realistic increase in completed jobs, not only to the hope that growth will appear after the money arrives.

Frequently Asked Questions

What type of financing is often used for vans and tools? Equipment-focused financing is often used because the purchase is tied to a business asset.

Why do home-service companies value fixed payments? Because predictable payments are easier to manage around dispatch, payroll, and seasonal demand.

Should a company borrow for growth all at once? Not always. Borrowing in stages can reduce risk and make growth easier to track.

Final Thought

Good home-service financing supports capacity without overwhelming cash flow. Match the amount to the real growth plan, keep payments predictable, and leave room for slower months.
Hotel and Hospitality Financing: Renovations and Occupancy Cash Flow

How do you renovate rooms without losing the cash you need to survive a weak occupancy season? Hospitality businesses carry property costs, payroll, utilities, insurance, supplies, and guest-service expenses every day. Renovation can improve the asset, but it can also reduce available rooms while the work is underway. That is why the best business loans for a hotel are not simply the ones with the lowest advertised number. The payment must fit the occupancy cycle.


Understand Occupancy-Driven Cash Flow

Hotel cash flow changes with occupancy, average room revenue, group business, and seasonality. At the same time, many costs remain fixed. Payroll, utilities, insurance, franchise fees, property expenses, and debt service continue even when rooms are empty. Owners should understand the break-even level before adding another payment.

Small business loan rates matter, but the payment should be tested against the weak months. A low rate on a short term can still produce a large monthly obligation. A slightly higher rate on a structure that protects operating liquidity may be easier for the property to manage.

Separate Property Debt From Renovation Capital

Existing property debt and new renovation debt both draw from the same operating cash. Owners should list all current payments before sizing the renovation. A project that looks affordable by itself may be too heavy once mortgage, equipment, and other obligations are added.

Commercial business loans can support property-related needs, but the business should compare the total debt service after the project. The right question is not, ‘Can we get the loan?’ It is, ‘What does total monthly debt look like after the loan closes?’ That view prevents a good renovation from creating a bad capital structure.

Stage Improvements Around Occupancy

Phasing work can protect revenue. Renovating one floor, wing, or room group at a time may keep more inventory available for sale. The schedule should consider peak periods, group bookings, and major local events. Every closed room has an opportunity cost.

The renovation budget should include that lost revenue, not just construction expense. Owners should also include furniture, technology, permits, design, contingency, and reopening costs. A project that ignores lost room revenue can be underfunded before the first contractor invoice arrives.

Stress-Test a Weaker Season

Run a downside case with lower occupancy, softer room rates, one unexpected repair, and a delay in the renovation schedule. Then add the proposed loan payment. If the property still has enough cash for payroll and guest service, the plan has more resilience.

Business loan interest rates should be compared with this operating test. Financing cost is important, but liquidity is equally important in hospitality. A property that cannot serve guests because every dollar is committed to debt will not protect its long-term value.

How Money Man 4 Business Can Help Compare Hospitality Financing

Money Man 4 Business looks at the whole financing picture, not only the approval amount. Owners can compare monthly payments, true APR where available, term length, and the effect on working cash. Money Man 4 Business can also review whether a term loan, SBA option, consolidation, or another structure fits the need. The process includes CFO-level guidance backed by more than 34 years of experience. Depending on the program and underwriting, terms can be structured across a wide range, including longer repayment periods. The goal is simple: choose financing that the business can carry after the money arrives.

For hotel owners, Money Man 4 Business can combine the renovation payment with existing property debt and normal operating costs. The review can compare rate, term, true APR where available, and the cash reserve left after debt service. If expensive short-term obligations are already in place, the owner can also evaluate whether restructuring them first creates a safer renovation plan.

Hotel owners should review the renovation plan with operations staff, not only contractors. Front-desk, housekeeping, maintenance, and revenue teams can identify timing problems that affect guest experience or lost room nights. Their input helps the financing schedule reflect how the property actually operates during construction.

Before signing, put the proposed payment into a simple monthly forecast and compare it with the business’s weaker months. That single step often shows whether the structure is comfortable or whether the amount, term, or timing should change before the agreement is final.

Practical Planning Before You Apply

Hospitality owners should separate renovation work that protects the asset from upgrades designed to increase revenue. Replacing worn systems may be necessary even if it does not raise room rates immediately. A major room redesign may have a clearer revenue goal. This distinction helps management decide which projects must happen now and which can be phased.

Reserve requirements should be part of the financing model. A property needs cash for payroll, utilities, repairs, supplies, and guest recovery even during construction. Commercial business loans should not consume the reserve simply because the lender is willing to fund the project. Liquidity protects the guest experience while the renovation is still producing disruption.

Owners should also review debt with the property manager and accounting team. Existing mortgage payments, equipment leases, and other obligations may already be using a large share of cash. Business loan interest rates are only one part of the decision. Total monthly debt service shows whether the property can actually carry another obligation.

If a renovation is expected to raise room rates, use a conservative increase in the model. Guests may not accept the new price immediately, and competitors can respond. The best business loans should still work if the revenue improvement takes longer than planned. A project that requires perfect pricing from the first month leaves too little margin for error.

Finally, measure the result after reopening. Track occupancy, room revenue, guest feedback, operating costs, and debt service against the original plan. This shows whether the project is delivering the expected return and gives the owner better information for the next property improvement or financing decision.

Hotel owners should also plan around the renovation calendar. Closing too many rooms at once can reduce revenue faster than expected. Phasing the work may protect cash flow, even if the project takes longer. Commercial business loans should be tested against that reduced room count. Owners should also keep a repair reserve outside the renovation budget. A new lobby or guest room does not remove the risk of an HVAC failure, plumbing issue, or emergency repair elsewhere on the property. Small business loan rates are useful for comparison, but the full payment and reserve position matter more. The property should still have enough cash to protect the guest experience while debt is being repaid.

Franchise or brand requirements can also affect the budget. Some upgrades are mandatory, while others are optional improvements. Owners should separate the two. Mandatory work protects compliance. Optional work should have a clear reason, expected return, and realistic timeline before debt is added. That discipline keeps the renovation tied to property performance, not appearance alone. Cash still needs protection.


Frequently Asked Questions

Can hotel renovations be financed?

Yes, depending on the property, project, and lender. Owners should prepare a full renovation budget, schedule, and cash-flow forecast.

How should occupancy affect loan planning?

Use conservative occupancy assumptions, especially during renovation. The payment should still work when some rooms are offline or demand is weaker.

Is the lowest rate always the best hospitality loan?

No. Payment size, term, fees, flexibility, and operating liquidity matter too. The best structure is the one the property can carry safely.

Final Thought

Hospitality financing should improve the property without weakening service. Plan around occupancy, include lost-room revenue, and protect enough liquidity to run the hotel while the work is underway.

Trucking Company Financing: Plan Fuel, Repairs, and Fleet Cash Flow

When fuel, repairs, insurance, and payroll are due before customers pay, how much cash can one truck really carry? Trucking businesses often look profitable on a monthly report but still feel cash-starved during the week. Fuel is paid now. Drivers expect payroll on time. Repairs cannot always wait. Customer or broker payments may arrive later. That timing gap is why small business loans for trucking should be judged by cash flow, not only by the amount approved.


Map the Trucking Cash Cycle

Start with the cash cycle for each truck. List fuel, driver pay, insurance, tolls, maintenance, permits, and the truck payment. Then list when freight invoices are actually collected. The gap between those dates shows how much working cash the business needs to stay steady. It also shows why a high-revenue fleet can still struggle if collections are slow.

Business working capital loans may help with that gap, but only when the owner knows the size of the need. Borrowing should cover a measured timing problem, not a vague fear of running short. A good weekly forecast shows when cash is tight, which units are producing, and how much reserve is needed before another truck is added.

Separate Fleet Assets From Operating Cash

Buying a truck is different from buying diesel or covering payroll. A truck is a long-lived asset. Fuel and wages are operating costs. Those needs may require different financing structures. Using short-term money for a long-life asset can create a payment that is too aggressive. Using a long-term loan for a small temporary gap can also be inefficient.

Equipment financing can make sense when the asset itself creates revenue over several years. Working-capital financing may fit a shorter operating gap. Owners should avoid mixing the two without a reason. The financing term should reflect how long the funded need will produce value for the business.

Budget Downtime and Major Repairs

A truck earns nothing while it is down, but many costs keep running. That makes downtime one of the most important stress tests. Model what happens if a truck is out for one week, two weeks, or a full month. Include repair costs and the lost contribution from missed loads.

An equipment financing calculator can help estimate a payment on a replacement truck or major equipment purchase. The owner should then place that payment inside the downtime scenario. If the payment only works when every unit is running perfectly, the fleet may be borrowing too aggressively. A healthier deal leaves room for normal breakdowns and slower weeks.

Compare Financing by Monthly Cash Impact

Do not compare offers by approval amount alone. Compare the monthly payment, total fees, true APR where available, and how much cash remains after the payment. A lower payment may protect working capital, but the term should not be stretched without thinking about total cost. The goal is a balance between affordability and efficiency.

The same rule applies when adding trucks. Estimate cash generated per unit after fuel, driver pay, maintenance, insurance, and debt service. If the new unit does not create enough margin under a conservative forecast, more equipment may not improve the business. Growth should make the fleet stronger, not simply larger.

How Money Man 4 Business Can Help Structure Fleet Growth

Money Man 4 Business looks at the whole financing picture, not only the approval amount. Owners can compare monthly payments, true APR where available, term length, and the effect on working cash. Money Man 4 Business can also review whether a term loan, SBA option, consolidation, or another structure fits the need. The process includes CFO-level guidance backed by more than 34 years of experience. Depending on the program and underwriting, terms can be structured across a wide range, including longer repayment periods. The goal is simple: choose financing that the business can carry after the money arrives.

For trucking owners, that review can separate truck financing from operating needs and show where high-cost debt is draining the account. If several short-term obligations are pulling cash every week, consolidation may create a more predictable monthly structure. Any savings depend on the current debt and the new offer, but a clear comparison can show whether refinancing improves the fleet’s real cash position.

Fleet owners should also compare performance by truck. A unit that produces high revenue but consumes too much fuel, repair time, and debt service may not be helping the fleet. Simple unit-level reporting makes future borrowing decisions much clearer and can show whether the next dollar belongs in a new truck, a repair reserve, or debt reduction.

Before signing, put the proposed payment into a simple monthly forecast and compare it with the business’s weaker months. That single step often shows whether the structure is comfortable or whether the amount, term, or timing should change before the agreement is final.

Practical Planning Before You Apply

Fleet owners should also separate fixed costs from miles-driven costs. Insurance and truck payments continue even when a unit sits. Fuel and some maintenance rise with mileage. This split helps the company understand the minimum revenue each truck must produce before it contributes to overhead and profit. It also makes small business loans easier to evaluate because the new payment can be tested against a realistic break-even point.

A repair reserve should be treated as a normal fleet expense, not as leftover cash. Set aside money during strong weeks for tires, brakes, emissions systems, and major mechanical work. If every strong week is used to pay other bills, one breakdown can push the business toward expensive emergency borrowing. Business working capital loans work better when they support timing, not when they replace basic reserve discipline.

When a replacement truck is being considered, compare repair history with future payment cost. An older truck may appear cheaper because it has no loan, but repeated downtime can cost more than a predictable payment. Use an equipment financing calculator to compare the new payment with recent repair bills, lost loads, and maintenance time. The decision should be based on total fleet economics, not age alone.

Insurance renewals can also create large cash demands. Build those dates into the yearly forecast and avoid treating them as surprises. The same applies to registration, permits, and seasonal maintenance. Better planning can reduce the need for fast financing and give the owner more time to compare equipment financing or working-capital options on cost instead of urgency.

For owner-operators and small fleets, personal draws matter too. Taking too much cash from the company during strong months can leave the business short during repairs or slower freight periods. A simple rule is to pay the owner from a planned amount and let the fleet reserve build separately. That creates a stronger base for growth and a cleaner picture for future lenders.

A fleet should also track cost per mile after financing. That number shows whether a truck is earning enough to justify its debt. If maintenance rises or freight rates soften, the owner can react early. Small business loans work best when the payment still leaves room for fuel, payroll, insurance, and a repair reserve.


Frequently Asked Questions

Can financing cover truck repairs?

Yes, depending on the product and underwriting. Owners should first decide whether the repair is a short-term operating need or part of a larger equipment plan.

Should a truck loan term match the vehicle’s useful life?

Generally, the term should make sense for how long the truck is expected to produce value. A very short term can create unnecessary cash pressure.

How much cash reserve should a fleet keep?

There is no single number for every fleet. The reserve should reflect fuel, payroll, insurance, repair risk, and the time it usually takes to collect from customers.

Final Thought

A trucking loan should be built around the real cash cycle of the fleet. Measure each truck, plan for downtime, and choose payments that still work when the road is not perfect.

Landscaping and Seasonal Service Financing: Survive the Off-Season Without Overborrowing

Seasonal service businesses often earn money in waves. Landscaping, lawn care, irrigation, snow services, and outdoor maintenance can be very busy for part of the year and much quieter later on. Yet equipment payments, insurance, truck costs, and payroll do not disappear in the slow months. That is why many owners consider a working capital loan before the off-season starts. The key is planning early enough that financing becomes a tool, not a last-minute reaction.


Why the off-season causes stress

A seasonal company usually knows its weak period in advance. Even so, owners often wait until cash is already tight. By then, options may be narrower and urgency may push them toward expensive funding. A better approach is to look at the full year. If revenue falls every winter or every rainy season, the company should treat that pattern as normal and build a plan around it.

This is where small business funding should support timing rather than cover up a broken model. If the business has healthy busy-season margins and reliable returning customers, financing can smooth the calendar. If pricing is weak or collections are poor, the owner should fix those issues too. Borrowing works best when it supports a good business, not when it replaces one.

The most common uses for seasonal financing

Off-season financing usually goes toward payroll retention, truck and trailer expenses, repairs, insurance, rent, and early inventory buying. Some owners also use it to market spring services before the rush begins. Others use it to buy materials in advance at better prices. These are practical uses because they either protect the core team or help the business enter the next busy season ready to earn.

Owners comparing business working capital loans should separate must-pay expenses from optional spending. Keeping a reliable crew, repairing a mower fleet, or renewing commercial insurance may be essential. Expanding into a new service line may be optional. Clear priorities make it easier to decide how much to borrow and whether the expected return justifies the cost.

Which financing structures often fit better

A small line of credit can work well when cash needs are short and flexible. It allows the company to draw only what it needs and repay as revenue returns. A fixed term loan may work better if the owner already knows the amount required for winter carry, equipment upgrades, or pre-season spending. The better fit depends on whether the need is recurring, one-time, or a mix of both.

Many owners prefer business loans with monthly payments because monthly schedules line up better with budgeting and owner reviews. A predictable payment can be built into the off-season plan. Daily or very frequent withdrawals can be harder to manage when incoming cash is already thin. The payment schedule matters almost as much as the rate because timing pressure is often the real problem in a seasonal business.

How companies overborrow without noticing

Overborrowing often starts with optimism. The owner assumes next season will begin earlier, weather will be perfect, or every major client will renew. Those things may happen, but they should not be the base case. Borrowing should be tested against a slower start, a wet month, or a few delayed payments. If the business still looks comfortable, the amount is more realistic.

Another risk is using several small products instead of one clean structure. Stacked obligations can turn manageable expenses into a real squeeze. When comparing a working capital loan or other offers, look at the total monthly outflow after all debt payments. A business may survive one more funding advance, but survival is not the same as good planning.

A simple way to plan the borrowing amount

Build a month-by-month cash forecast. Start with fixed expenses. Add seasonal payroll decisions, maintenance, renewals, and tax obligations. Then estimate conservative off-season revenue. The gap between those numbers gives a starting point. From there, reduce the amount if some spending can wait or if the owner can save more during the busy season. Borrowing should fill a real need, not create a larger cushion than necessary.

When used carefully, small business funding can help a seasonal company keep its crew, protect equipment, and start the next season stronger. The strongest borrowing decisions usually combine financing with better cash habits. That may mean setting aside a reserve during peak months, tightening invoicing, and avoiding unnecessary draws during the slow period.


How Money Man 4 Business helps seasonal service owners

Money Man 4 Business helps owners compare financing based on real business cycles, not just approval size. A landscaping or service company can review how much to borrow, what payment schedule fits, and whether a term loan, line of credit, or another option makes the most sense. The discussion focuses on operating reality, including crew needs, vehicle costs, equipment upkeep, and timing of peak work.

Money Man 4 Business brings more than 34 years of experience and a CFO-level view of cash flow to the process. That helps owners compare business working capital loans in a more disciplined way. The goal is to protect cash through the slow season and arrive at the next busy season ready to earn, not weighed down by a structure that drains the company before work picks up again.

Use the busy season to improve the slow-season plan

A seasonal business becomes easier to finance when its plan is simple: here are the fixed costs, here is the likely slow-season revenue, and here is the shortfall. Framing the need this way turns a working capital loan into a targeted business tool rather than a vague emergency response. Clear planning protects the next season as much as the current one.

Owners should also gather renewal data, customer retention patterns, and maintenance schedules before applying. Lenders and advisors can make better recommendations when they understand how many contracts are recurring and what equipment must be ready before the next rush. Companies comparing business loans with monthly payments should also estimate when revenue usually starts to rebound so repayment lines up with the company’s real calendar.

The best off-season funding plans usually begin during the busy season. When revenue is strong, the owner can review which expenses are always waiting in the slow months and which ones can be reduced. Saving part of peak-season profit may lower the borrowing need later. Then, if business working capital loans are still needed, the company borrows for a smaller and more defined gap instead of carrying the whole off-season on debt alone.

A useful final check is to compare the off-season plan with the cash left after every required payment. If the company still has room for fuel, repairs, insurance, and payroll, the structure is more realistic. Owners reviewing business loans with monthly payments should also confirm when the first stronger revenue month usually arrives. That gives the business a clear point where the seasonal bridge begins to unwind instead of becoming permanent debt.

Frequently Asked Questions

Should a landscaping company borrow before the off-season starts? Often yes, if the need is predictable. Planning early usually gives the owner more choices and less pressure.

What is a good use of seasonal financing? Payroll retention, vehicle upkeep, insurance, and pre-season marketing are common examples.

Can monthly payment financing work for seasonal businesses? Yes. Many owners prefer it because it is easier to budget and track across a full month.

Final Thought

Seasonal financing should bridge a known gap, not create a new one. Borrow early, borrow carefully, and choose a structure that the company can still carry when work slows down.

Daycare Business Financing: Staffing, Enrollment, and Facility Costs

What happens when payroll must be paid every two weeks but enrollment revenue changes by the month? Childcare centers have a cost structure that leaves little room for careless borrowing. Staffing, rent, insurance, supplies, food, licensing, and facility maintenance continue even when enrollment dips. Easy business loans may sound attractive, but the real goal is a payment the center can support at conservative enrollment.


Map the Childcare Cost Structure

Start with fixed and variable costs. Payroll is usually one of the largest items. Add rent or property expense, insurance, food, classroom supplies, software, cleaning, licensing, maintenance, and training. Then separate costs that rise with enrollment from costs that remain even when a classroom has vacancies.

This map helps with small business loan requirements because it shows the lender how the center operates. It also helps the owner see how much room exists for a new monthly payment. A financing plan should be based on the center’s normal cost structure, not on a perfect month.

Treat Enrollment Changes as a Cash-Flow Variable

Enrollment is not always stable. Families move, children age into new programs, and seasonal changes can affect attendance. A center should model a conservative enrollment level and a stronger level. The difference shows how sensitive cash flow is to vacancies.

This matters when owners ask how to qualify for business loan with monthly payments. The strongest file shows that the business can carry the payment without relying on maximum capacity. A conservative forecast gives both the owner and lender a more realistic view of repayment ability.

Finance Expansion Only After Staffing Is Included

A new classroom requires more than furniture. It may require teachers, aides, training, supplies, licensing work, safety changes, and additional insurance. Owners should include the full staffing cost before deciding that an expansion will pay for itself.

A room that is built but not fully staffed does not create the expected revenue. The budget should show when staff are hired, when enrollment begins, and how long it may take to fill the space. Financing should support that ramp, not assume immediate full occupancy.

Choose a Monthly Payment the Center Can Support

Business loans with monthly payments are easier to place inside a center’s budget than frequent daily deductions. Even so, the monthly amount must be realistic. Test it at conservative enrollment and include one unexpected facility cost or staffing issue.

If the payment only works at full enrollment, the loan is too dependent on perfect conditions. A smaller project, longer term, or phased expansion may be healthier. Financing should protect the center’s ability to pay staff and maintain care quality during ordinary fluctuations.

How Money Man 4 Business Can Help Structure Childcare Financing

Money Man 4 Business looks at the whole financing picture, not only the approval amount. Owners can compare monthly payments, true APR where available, term length, and the effect on working cash. Money Man 4 Business can also review whether a term loan, SBA option, consolidation, or another structure fits the need. The process includes CFO-level guidance backed by more than 34 years of experience. Depending on the program and underwriting, terms can be structured across a wide range, including longer repayment periods. The goal is simple: choose financing that the business can carry after the money arrives.

Money Man 4 Business can help a childcare owner compare the proposed payment with payroll, enrollment, and facility costs. The review can also identify whether existing high-cost debt should be consolidated before expansion. The aim is to keep debt service predictable and leave enough cash for the people and operations that make the center work.

Childcare owners should also build a reserve plan into the financing decision. A center with a full classroom today can still face vacancies or staff changes later. Rebuilding cash during stronger enrollment months helps the business avoid reaching for expensive emergency money when normal changes occur.

Before signing, put the proposed payment into a simple monthly forecast and compare it with the business’s weaker months. That single step often shows whether the structure is comfortable or whether the amount, term, or timing should change before the agreement is final.

Practical Planning Before You Apply

Licensing and safety costs should be planned before construction starts. A facility change may require inspections, fencing, security, fire-safety work, accessibility improvements, or classroom adjustments. The exact rules depend on the location, so owners should confirm requirements with the appropriate local authorities. A loan budget is stronger when these costs are identified early instead of discovered near opening.

Staffing ratios can also affect how quickly a new classroom becomes profitable. Adding children may require another teacher before the room reaches full revenue. Owners should model the staffing step carefully. Business loans with monthly payments should be tested after the new payroll cost is added, not before it.

Parents often pay on a schedule that does not perfectly match payroll and rent dates. A simple weekly forecast can show where those timing gaps appear. Easy business loans should not become the default response to predictable timing. If the pattern repeats every month, the center may need a reserve policy or a different billing process rather than another short-term loan.

Owners preparing small business loan requirements should keep enrollment reports, bank statements, financial statements, current debt information, and a detailed project budget ready. Organized records do not change the underlying economics, but they make underwriting faster and help the owner answer questions with confidence.

A final test is to ask what happens if hiring takes longer than expected. A new classroom may be ready before qualified staff are in place. If the loan payment begins immediately, the center needs enough reserve to carry the space until staffing and enrollment catch up. Growth should be paced around both people and capital.

Childcare owners should also include the cost of staff recruitment and training. A new classroom may be ready before the right teacher is hired. That delay can postpone enrollment revenue while rent and other costs continue. Business loans with monthly payments should be tested against that slower opening. Owners should also watch tuition collection patterns. Late family payments can create pressure even when enrollment is strong. A weekly cash forecast helps show when payroll, food, supplies, and rent are due. Small business loan requirements are easier to prepare when enrollment records, staffing plans, licenses, and financial statements are organized early. Clear records also help the owner decide whether the expansion is affordable before submitting an application.

Owners should also avoid using maximum licensed capacity as the base forecast. A center may be licensed for more children than it can staff profitably. The safer model uses realistic classroom ratios, normal vacancies, and the actual hiring market. That creates a better view of the payment the center can carry. That approach also gives lenders a more credible picture of future cash flow and helps the owner avoid stretching the center too far. That protects care quality too.

That discipline matters.


Frequently Asked Questions

Can childcare businesses finance facility improvements?

Yes, depending on the lender and use of funds. Owners should prepare a detailed project budget that includes staffing and operating costs.

How should enrollment be stress-tested?

Use a conservative enrollment level, not only maximum licensed capacity. Test what happens if several spaces remain open longer than expected.

What information may lenders review before approval?

They may review revenue, bank statements, financial statements, credit, time in business, existing debt, and the specific use of funds.

Final Thought

Childcare financing should support care, not compete with it. Plan staffing first, use conservative enrollment, and choose a payment that still leaves room for normal center expenses.

Salon and Spa Financing: Renovations, Staffing, and Booking Growth

How do you finance chairs, treatment rooms, staff, and marketing when bookings may take months to ramp up? A salon or spa expansion often requires spending before the new space produces steady revenue. That can make small business financing useful, but only when the budget includes the slow start. Owners searching small business loans online should plan around realistic bookings, not full capacity on day one


Build the Real Expansion Budget

Start with the complete project. Include construction, chairs, wash stations, treatment equipment, deposits, licenses, signage, software, initial supplies, and marketing. Then include the staffing cost needed to operate the added capacity. A room is not productive without the person who serves the client.

Many salon projects run over budget because the owner focuses on visible items and forgets installation, permits, or opening inventory. A complete budget reduces the chance of borrowing twice. It also gives the lender a clearer picture of how the funds will be used.

Model the Booking Ramp-Up

New chairs or treatment rooms rarely reach full utilization in the first month. Build a ramp that starts conservatively and increases as marketing, reviews, and repeat clients grow. The ramp should include no-shows, staff training, and the time needed to build a new book of business.

This matters for business loan eligibility because lenders look at repayment capacity, not just the beauty of the project. A realistic ramp is stronger than an aggressive forecast that assumes every slot is filled. It also helps the owner choose a payment that works while the new area is still building demand.

Choose Financing Around Recurring Monthly Cash Flow

The loan payment competes with rent, payroll, supplies, software, and marketing every month. Test the payment against a slow booking month. If the salon still has room to operate, the structure may be healthy. If the payment only works at peak utilization, the project may need to be smaller or phased.

Owners often ask what credit score is needed for a business loan. Credit matters, but it is not the only factor. Lenders may also review time in business, revenue, cash flow, debt, and the specific purpose of the financing. A stronger overall file can matter as much as one score.

Use Credit Carefully for Cosmetic Improvements

Not every renovation produces revenue. Better lighting, paint, and finishes can improve the client experience, but they should be separated from assets that clearly increase capacity. A new treatment room may create new appointments. An expensive decorative feature may not.

That does not mean cosmetic work is always a bad use of funds. It means the owner should know why the spending matters. Finance revenue-producing improvements first, then decide how much additional debt the business can safely carry for appearance and branding.

How Money Man 4 Business Helps Service Businesses Test Affordability

Money Man 4 Business looks at the whole financing picture, not only the approval amount. Owners can compare monthly payments, true APR where available, term length, and the effect on working cash. Money Man 4 Business can also review whether a term loan, SBA option, consolidation, or another structure fits the need. The process includes CFO-level guidance backed by more than 34 years of experience. Depending on the program and underwriting, terms can be structured across a wide range, including longer repayment periods. The goal is simple: choose financing that the business can carry after the money arrives.

Money Man 4 Business can help salon and spa owners test the project against realistic bookings and monthly expenses. The review can compare online offers with term loans and SBA-style options where appropriate. If existing short-term debt is already reducing cash flow, the owner can also look at consolidation before adding expansion debt.

Salon owners can also protect cash by phasing the project. Opening two treatment rooms first may be safer than building four at once if demand is still growing. A phased plan can reduce the first borrowing amount, provide real booking data, and give the owner more confidence before the next stage is funded.

Before signing, put the proposed payment into a simple monthly forecast and compare it with the business’s weaker months. That single step often shows whether the structure is comfortable or whether the amount, term, or timing should change before the agreement is final.

Practical Planning Before You Apply

Service mix matters when a salon expands. Hair, nails, skin, massage, and other services can have different equipment costs, margins, and booking patterns. The owner should model each new service separately instead of assuming the entire expansion will perform the same way. That makes small business financing more closely tied to the revenue each area can realistically produce.

Staffing structure also matters. Employees, booth renters, and commission-based staff affect cash flow differently. The owner should know how payroll, commissions, taxes, and product costs change as bookings increase. A renovation may look affordable until the added staffing cost is included. The complete model should show both the new revenue and the new labor burden.

Owners searching small business loans online should keep a short comparison sheet. Include amount received, monthly payment, true APR where available, fees, term, prepayment rules, and any collateral or guarantee. This makes online offers easier to compare and reduces the chance that speed or a large approval amount distracts from the real cost.

Business loan eligibility can also improve when the owner cleans up records before applying. Keep business and personal spending separate, reconcile deposits, reduce avoidable overdrafts, and prepare recent financial statements. These steps do not guarantee approval, but they make the file easier to understand and help the lender see the business more accurately.

Marketing should be included in the ramp-up budget. New rooms or chairs do not create demand by themselves. Set aside funds for launch offers, local promotion, referral campaigns, or digital advertising. The loan should support the path from renovation to bookings, not stop at the moment construction is complete.

Salon owners should also separate renovation costs from opening cash. The project may be finished, but the business still needs money for payroll, supplies, utilities, and marketing while bookings build. Small business financing should leave room for that ramp-up period. Owners should also track revenue by service and by provider. That shows whether the expansion is working as planned. If one room or service is slow, the owner can adjust before the loan payment becomes a problem. When comparing small business loans online, focus on monthly payment, term, fees, and true APR where available. A fast approval matters less than a payment the salon can support during ordinary weeks.

A strong salon plan also protects the owner from overbuilding. More chairs or rooms only help when demand can support them. Start with realistic capacity, then expand again when utilization proves the need. This keeps debt aligned with actual client growth. The goal is steady growth, not empty capacity financed with debt. That keeps the plan practical.


Frequently Asked Questions

Can a salon finance a renovation?

Yes, depending on the lender and project. Owners should prepare a detailed use-of-funds budget and realistic revenue ramp.

How should a salon estimate ramp-up revenue?

Use current booking history, expected staff capacity, marketing plans, and conservative utilization assumptions. Avoid assuming every chair or room is full immediately.

Does credit score determine the whole financing decision?

No. Credit is important, but lenders may also review revenue, cash flow, time in business, existing debt, and the purpose of the loan.

Final Thought

A salon expansion should feel manageable before opening day. Build the full budget, assume bookings take time, and choose a monthly payment that still works in a slower season.

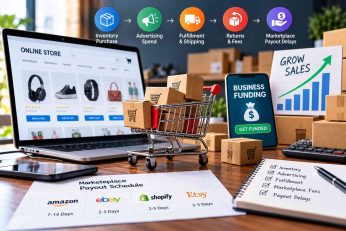
E-Commerce Business Financing: Inventory, Ads, and Payout Delays

Can rising sales still create a cash shortage when advertising and inventory are paid before marketplace payouts arrive? Yes. E-commerce growth often uses cash before it produces cash. Ads are paid today. Inventory may be purchased weeks in advance. Fulfillment and returns reduce the amount that finally reaches the bank. Online business loans can help with timing, but only when the owner understands the real contribution margin behind each sale.


Why Growth Can Consume E-Commerce Cash

Sales growth looks positive on a dashboard, but it can create a larger funding need. More orders often require more stock, more ad spend, higher fulfillment costs, and more working capital tied up in returns. Marketplace payout schedules can add another delay between the sale and the cash deposit.

That is why business funding should be based on the cash cycle, not only on revenue growth. Owners should map when inventory is purchased, when ads are paid, when orders ship, and when marketplaces release funds. The gap between those events is the real financing need.

Track Contribution Margin Before Borrowing

Revenue is not the same as profit. Before financing growth, calculate contribution margin after product cost, advertising, fulfillment, marketplace fees, returns, and shipping support. If the margin is shrinking, borrowing to increase sales may simply increase the problem.

A useful rule is to finance a repeatable engine, not a hopeful one. If a product already sells with stable margins, capital can help scale it. If acquisition cost is rising and returns are unpredictable, more debt may add risk faster than it adds profit. The owner should know the margin before choosing the loan.

Finance the Timing Gap, Not Headline Sales

Size financing around inventory turns and payout timing. A business doing $200,000 in monthly sales may not need $200,000 in financing. It may only need enough to cover the temporary gap between stock purchases and collected cash. Smaller, measured borrowing often costs less and leaves more room for future needs.

Online business loan monthly payment options can make planning easier because the payment can be placed inside a monthly forecast. The owner should still test that payment during a weak sales month. Financing should create room for inventory and growth, not consume the same cash the business needs to reorder its best products.

Review Fast Online Offers Carefully

Fast business funding online can be attractive when inventory is about to run out. Speed is useful, but it should not replace comparison. Review the total payback, payment frequency, fees, true APR where available, and whether payments begin before the new inventory has time to sell.

Daily or weekly withdrawals can be especially hard on an online seller with uneven payout timing. A predictable monthly structure may be easier to manage. The best offer is not always the one that arrives first. It is the one that leaves enough cash inside the business after each payment.

How Money Man 4 Business Helps Online Sellers Choose Structure Over Speed

Money Man 4 Business looks at the whole financing picture, not only the approval amount. Owners can compare monthly payments, true APR where available, term length, and the effect on working cash. Money Man 4 Business can also review whether a term loan, SBA option, consolidation, or another structure fits the need. The process includes CFO-level guidance backed by more than 34 years of experience. Depending on the program and underwriting, terms can be structured across a wide range, including longer repayment periods. The goal is simple: choose financing that the business can carry after the money arrives.

For an online seller, Money Man 4 Business can compare financing against inventory turns, payout delays, and contribution margin. The owner can see whether the business really needs more debt, a longer term, or a cleanup of existing high-cost obligations first. That keeps growth funding tied to the economics of the store instead of the urgency of the next inventory order.

Online sellers should review the funding plan after each major inventory cycle. If the store repeatedly needs new debt before the previous inventory is converted to cash, the problem may be turnover, margin, or payout timing. That pattern deserves attention before the owner adds another loan simply because sales are growing.

Before signing, put the proposed payment into a simple monthly forecast and compare it with the business’s weaker months. That single step often shows whether the structure is comfortable or whether the amount, term, or timing should change before the agreement is final.

Practical Planning Before You Apply

E-commerce owners should track inventory by product, not only in total. One fast-moving item can hide several slow products that are tying up cash. Borrowing more for inventory without fixing slow stock can deepen the problem. Business funding should follow items with proven demand and healthy contribution margin, while weaker products are reduced, bundled, or cleared deliberately.

Advertising also needs a repayment window. If paid ads create sales today but payouts arrive later, the business must carry the ad cost during the delay. That is manageable when the return is consistent. It becomes risky when campaigns are still being tested. Online business loans should support known economics, not experiments that have not shown a reliable return.

Returns deserve their own line in the forecast. A surge in sales can be followed by a surge in refunds, replacement shipping, and restocking work. If the loan payment arrives at the same time, cash can tighten quickly. Owners should use their normal return rate and a higher stress-test rate before choosing a financing amount.

Marketplace concentration also matters. A seller that depends on one platform is exposed to payout holds, account reviews, fee changes, and ranking shifts. A larger reserve can protect the business from those interruptions. Fast business funding online may appear attractive during a hold, but the owner should still compare total cost and avoid creating a second problem while waiting for the first one to clear.

Finally, use online business loan monthly payment options inside a rolling forecast after funding. Update sales, ad spend, inventory purchases, payouts, and debt service every week. That habit shows whether the loan is creating the expected benefit. If the store needs another loan before the first one has produced enough cash, the owner should investigate margin and turnover before borrowing again.

E-commerce owners should also plan for platform changes. A marketplace may change fees, hold funds, or reduce account visibility. That can affect cash quickly. Business funding should not assume every sales channel performs the same way forever. Keep enough reserve to handle a payout delay or advertising setback. Online business loans are most useful when they support proven products and clear margins. They are much riskier when they are used to chase sales without knowing whether those sales actually produce cash after returns, fees, and advertising costs.

One simple rule helps: finance a repeatable model, not a hopeful one. If the product already sells with a healthy margin, capital can support scale. If the economics are still uncertain, more borrowing may only increase the size of the uncertainty.


Auto Repair Shop Financing: Parts, Equipment, and Cash Flow

If a diagnostic system or lift fails today, can your shop afford to wait – and can it afford the wrong financing? Auto repair shops have two very different capital needs. Some spending is urgent, such as replacing failed equipment. Other spending is strategic, such as adding a lift or alignment system to increase capacity. Small business equipment financing can help, but owners should separate emergencies from planned upgrades before choosing a loan.


Separate Emergency Repairs From Planned Upgrades

An emergency repair is about restoring current capacity. A planned upgrade is about creating new capacity or efficiency. Those goals should be modeled differently. An urgent replacement may have limited options because the shop needs to reopen a bay quickly. A planned purchase gives the owner more time to compare terms and expected return.

Equipment financing should be tied to the useful life and revenue impact of the asset. A lift that will serve the shop for years should not automatically be funded with an extremely short repayment period. A small repair, however, may not justify a long loan. Match the debt to the problem.

Build the Full Equipment and Installation Budget

The sticker price is only part of the project. Diagnostic systems may require software, subscriptions, training, or calibration. Lifts and alignment equipment may require electrical work, concrete changes, delivery, and installation. A complete budget prevents the owner from closing a loan and then discovering another unfunded cost.

Equipment loan rates matter, but a complete budget matters just as much. A lower rate does not help if the shop underestimated the project by 20%. Build the full number first, then compare financing. That makes payment planning much more accurate.

Track Parts and Technician Cash Flow

Parts and payroll often leave the account before the customer or fleet account pays. That can create pressure during busy weeks. Shops with commercial accounts may wait longer for payment than retail customers. Owners should separate equipment debt from day-to-day working cash so one does not hide problems in the other.

A small business loan payment calculator can estimate the monthly obligation on a planned purchase. Place that payment beside payroll, rent, parts, and normal overhead. If the new payment forces the shop to rely on credit cards for everyday parts, the equipment deal may be too aggressive.

Test the Payment Against Slower Weeks

Repair shops are not equally busy every week. Weather, seasonality, staffing, and warranty work can change revenue. Test the new payment against a conservative month, not the best month of the year. Also model one unexpected repair to the new equipment or one technician vacancy.

The strongest equipment purchase creates enough capacity or efficiency to carry its own payment with room left over. If the return depends on every bay staying full, the shop may need a smaller project or a longer term. Good financing creates breathing room, not constant pressure.

How Money Man 4 Business Can Compare Equipment and General Financing

Money Man 4 Business looks at the whole financing picture, not only the approval amount. Owners can compare monthly payments, true APR where available, term length, and the effect on working cash. Money Man 4 Business can also review whether a term loan, SBA option, consolidation, or another structure fits the need. The process includes CFO-level guidance backed by more than 34 years of experience. Depending on the program and underwriting, terms can be structured across a wide range, including longer repayment periods. The goal is simple: choose financing that the business can carry after the money arrives.

Money Man 4 Business can help an auto shop compare the equipment purchase with the rest of the business cash flow. The review can include expected revenue from the new asset, monthly payment size, true cost, and whether other high-cost debt should be consolidated first. That keeps the new equipment from being added to an already stressed debt structure.

Shop owners should also track how often the new equipment is actually used. If utilization stays low, the expected return may not appear. That information can guide staffing, marketing, pricing, and the timing of the next equipment purchase. Financing works best when the shop treats the asset as an operating investment, not just a new tool.

Before signing, put the proposed payment into a simple monthly forecast and compare it with the business’s weaker months. That single step often shows whether the structure is comfortable or whether the amount, term, or timing should change before the agreement is final.

Practical Planning Before You Apply

Repair-shop owners should estimate the revenue capacity created by each new asset. A second lift, alignment rack, or diagnostic system should either increase the number of jobs, reduce outside work, or improve labor efficiency. If the benefit cannot be described clearly, the shop may be buying equipment before it has enough demand to support it.

Parts credit should be reviewed separately from equipment financing. Supplier accounts can help the shop manage normal parts purchases, but they can also hide weak cash flow if balances keep rising. Before taking new small business equipment financing, check whether supplier balances and credit cards are already carrying too much of the day-to-day operation.

Technician productivity also affects the return. A new machine may save time, but only if staff are trained and the workflow uses it well. Include training hours and learning time in the launch plan. The monthly payment starts quickly, while the full operating benefit may take several weeks to appear.

Use a small business loan payment calculator to compare more than one term. Then add the full project cost, not just the equipment price. A longer term may lower the payment, but the owner should also review total interest and the expected life of the asset. The best structure balances monthly affordability with reasonable total cost.

One more test is useful: ask what happens if a key technician leaves. If the equipment depends on one person, the shop should have a training or hiring plan before borrowing. Good equipment can still become an expensive idle asset when staffing is overlooked. Financing and workforce planning should move together.

Shop owners should also review how quickly new equipment pays for itself. Estimate added jobs, labor hours saved, and outside services that can now stay in-house. Then compare that benefit with the monthly payment. Small business equipment financing is easier to justify when the asset has a clear revenue role. Owners should also plan for software subscriptions, calibration, and service contracts. Those costs continue after installation. Equipment loan rates matter, but the full monthly cost matters more. A lower rate does not help if the total project still leaves too little cash for parts, payroll, and normal shop expenses.

It also helps to compare repair history before replacing equipment. A machine that fails often may cost more in downtime than a new payment would cost. That comparison turns the financing choice into an operating decision, not just a borrowing decision. That protects daily operations too.


Frequently Asked Questions

Can an auto shop finance diagnostic equipment?

Yes, many equipment programs can cover diagnostic systems and related business equipment, subject to underwriting and lender terms.

Should emergency repairs use the same financing as planned upgrades?

Not always. Emergency needs are short and urgent, while planned upgrades may support a longer-term investment case. The structure should match the purpose.

How do I estimate an affordable equipment payment?

Estimate the payment, then place it inside a conservative monthly cash-flow forecast that includes payroll, rent, parts, and slower weeks.

Final Thought

Auto-shop financing should keep bays productive without draining the parts and payroll account. Fund the right asset, include installation costs, and test the payment before committing.

Cash-Flow Recovery After Business Debt Consolidation

If consolidation frees thousands of dollars each month, will that cash rebuild the business or disappear into new spending? The months after refinancing can decide whether recovery lasts. Lower payment pressure may create room the business has not had for months. Treat that relief as a financial resource. Before seeking more small business funding, use part of the new cash flow to rebuild reserves. It may also need to catch up taxes, vendors, or other critical obligations. Better financing should do more than lower today’s payment. It should reduce the chance of another emergency loan tomorrow. The freed cash can disappear quickly if management treats it as extra spending money. A recovery plan gives that money a clear job before new expenses appear.


Treat Monthly Savings as a Recovery Resource

The first months after consolidation matter. Replacing several frequent payments may make the business feel stronger immediately. That does not mean every saved dollar should be spent. New inventory, marketing, equipment, or owner distributions may all be tempting. Some investment may make sense later. Stabilization should come first. Use the monthly savings to protect payroll and stay current on taxes. Bring supplier payments back to normal and reduce overdrafts. If other obligations remain overdue, create a catch-up schedule. The business should become less dependent on emergency approvals. Management can make progress visible in the budget. Create a monthly ‘cash-flow dividend’ equal to the reduction in debt service. Assign that amount to reserves and overdue obligations first. Use it for selected growth projects only after stabilization targets are reached. This does not mean growth must stop. It means growth spending should follow basic stabilization. Payroll, taxes, vendors, and reserves need enough support first.

Build a Minimum Cash Buffer

There is no reserve percentage that fits every business. A practical cash buffer should reflect actual fixed costs and volatility. Start with payroll, rent, taxes, insurance, essential software, and supplier needs. Then consider how long customers usually take to pay. Seasonality also matters. A company receiving daily payments may need a different reserve from a contractor. The contractor may wait 45 days for receivables. The goal is enough liquidity to absorb an ordinary surprise without new debt. If cash is tight, begin with a modest target. Build it gradually each month. Even one payroll cycle in reserve can change decision-making. Not every short-term problem then feels like an emergency. Reserve targets can also be built in stages. Start with one payroll cycle. Then aim for a month of fixed overhead and a larger seasonal cushion. Smaller stages can make the target easier to manage. The target should also reflect concentration risk. A business that depends on one large customer or one critical supplier may need a larger cushion.

Repair Vendor and Banking Relationships

Payment relief can also repair relationships strained during the debt cycle. Repeated overdrafts and late supplier payments can damage trust. Returned ACH items or last-minute extensions can add fees as well. Once cash flow improves, reduce those problems. Keep enough money in the operating account. Pay key vendors on agreed terms. Where practical, keep tax funds separate from working cash. Stronger account behavior can present a cleaner financial picture later. That can matter when the company seeks business capital loans or other financing. Recovery is not only about building a separate savings account. The full cash-flow system should become more dependable. Repairing relationships may also require direct communication. Speak with important vendors and ask whether better payment terms can return. Review bank fees and overdraft settings too. Better operating relationships can reduce future emergency liquidity needs. Better payment behavior can also lower avoidable fees. Fewer overdrafts, returned payments, and urgent extensions leave more cash available for normal operations.

Set Rules Before Taking New Debt

Decide in advance what would justify new borrowing. New debt should have a clear purpose or repayment source. It may finance equipment that expands capacity. It may also fund inventory with reliable demand. Another use could be a receivable tied to completed work. Borrowing only because cash is available is a warning sign. Set internal rules before the next request. How much reserve must remain after closing? What monthly payment can the business safely support? What return should the project produce? How quickly should the cash come back? These questions make future small business funding decisions more disciplined. They also reduce the risk of returning to emergency borrowing. Write the rules down. Where possible, involve more than one decision-maker. A short approval checklist can cover purpose, repayment source, payment, expected return, and minimum cash remaining. Review these rules before each financing request, not after approval. A written standard makes it easier to reject an offer that does not fit the business.

How MM4B’s CFO Support Can Extend Beyond Closing

Money Man 4 Business treats financing as part of the wider cash-flow decision. After a qualifying consolidation, the owner still needs a plan for the cash saved each month. Clients can work with a CFO with 34+ years of experience. That support can help review operating needs, reserve targets, and future borrowing capacity. MM4B can also help separate two different situations. One business may need fresh capital for growth. Another may need to strengthen reserves and the balance sheet first. The value of consolidation is not only one lower payment. It is the chance to operate with less constant pressure. The recovery period is also a good time to review pricing and margins. Lower debt service helps cash flow. It will not fix products or jobs that remain underpriced. Consolidation can create room to improve the operation, but it cannot replace that work. Owners should use the breathing room to fix recurring operating problems as well. Better margins and collections make the recovery more durable than lower debt service alone.


Frequently Asked Questions

What should I do with the cash saved after consolidation?

Prioritize essential operations, overdue obligations, taxes, supplier relationships, and a practical cash reserve before treating the savings as money available for new expansion.

How large should a business reserve be?

There is no single correct amount. Base the target on payroll, fixed expenses, supplier cycles, receivable timing, seasonality, and the level of volatility in the business.

When is it safe to borrow again?

When the new financing has a clear business purpose, the company has enough cash to support the payment, and the debt will not force the business back into emergency borrowing during a normal slow period.

Use the Breathing Room to Make the Next Emergency Less Dangerous

Cash-flow relief creates a chance to rebuild financial margin. Protect payroll, restore vendor relationships, and build reserves. Set clear rules for future borrowing as well. Money Man 4 Business can help owners look beyond the refinance itself. Future financing should support growth instead of replacing a missing cash buffer. Track reserve balances and debt service on the same monthly dashboard. If reserves are not growing after payments fall, find where the freed cash is going. Recovery should become visible over time. Look for fewer overdrafts, stronger supplier terms, current taxes, and a growing liquidity cushion. Management can set monthly checkpoints for the reserve. Small, steady gains are easier to track and can show whether the recovery plan is working.

New Business Tax Laws 2025 & How to Legally Reduce Business Taxes in the USA

New business tax laws 2025 are here, and understanding them can help businesses save money and stay compliant. Learning how to reduce business taxes legally is essential for small business owners looking to optimize their financial strategies. This guide covers everything you need to know about business tax deductions 2025, small business tax savings, and the latest updates in IRS regulations.

New Business Tax Laws 2025: Key Updates

As we enter 2025, the landscape of business taxation in the U.S. is evolving with several key changes that business owners need to be aware of. These changes impact small businesses, corporations, and self-employed individuals. Here’s what you need to know:

1. Adjustments to Corporate Tax Rates in 2025

One of the most significant updates in 2025 is the potential revision of corporate tax rates. While the federal corporate tax rate has remained at 21%, discussions in Congress may introduce new brackets for different revenue levels. Small businesses earning below a certain threshold might see reduced tax rates.

2. Section 179 Deduction Updates in 2025

For 2025, the Section 179 deduction limit has increased, allowing businesses to deduct the full cost of qualifying equipment purchases up to $1.2 million (previously $1.16 million). This is a great benefit for businesses investing in new technology, machinery, or software.

3. R&D Tax Credit Expansion for Small Businesses

Businesses involved in research and development may qualify for expanded R&D tax credits, especially small businesses and startups. The IRS has revised the eligibility criteria, making it easier for companies to claim tax benefits for innovation.

4. Small Business Pass-Through Deduction (QBI) in 2025

The Qualified Business Income (QBI) deduction, which allows pass-through entities (LLCs, S-Corps, sole proprietorships) to deduct up to 20% of qualified income, remains in effect. However, income limits for eligibility have been adjusted for 2025.

5. Enhanced Energy Efficiency Tax Credits in 2025

Businesses investing in green energy solutions—such as solar panels, energy-efficient buildings, or EV charging stations—can claim higher federal energy tax credits. New incentives have been introduced to promote sustainability in business operations.


How to Reduce Business Taxes Legally in 2025

As tax laws evolve, businesses should adopt smart tax strategies to minimize liabilities and maximize savings. Here are the best legal ways to reduce business taxes in 2025:

1. Maximize Business Tax Deductions in 2025

  • Deduct business expenses such as office rent, supplies, utilities, travel, and insurance.
  • Use the home office deduction if you operate your business from home.
  • Claim vehicle deductions if you use your car for business purposes.

2. Utilize Section 179 & Bonus Depreciation in 2025

  • Invest in new equipment, technology, or business property and deduct the full cost under Section 179.
  • Take advantage of bonus depreciation for assets purchased before the end of 2025.

3. Structure Your Business for Tax Savings in 2025

  • Consider switching from an LLC to an S-Corp to save on self-employment taxes.
  • If your business earns high revenue, exploring a C-Corp structure might offer tax benefits.

4. Take Advantage of Tax Credits for Small Businesses in 2025

  • Claim R&D tax credits if your business develops new products, software, or processes.
  • Use the Work Opportunity Tax Credit (WOTC) when hiring employees from targeted groups.
  • Apply for energy-efficient business tax credits if you invest in renewable energy solutions.

5. Fund Retirement & Employee Benefits for Tax Savings

  • Contribute to a 401(k), SEP IRA, or Solo 401(k) to reduce taxable income.
  • Offer health insurance benefits to employees and claim tax deductions for contributions.

6. Plan for Estimated Quarterly Tax Payments in 2025

  • Avoid IRS penalties by making quarterly estimated tax payments based on your earnings.
  • Work with a tax professional to ensure you’re paying the right amount throughout the year.

7. Work with a CPA or Tax Advisor to Reduce Business Taxes

  • A tax professional can help identify deductions, credits, and tax-saving strategies tailored to your business.
  • They can also ensure compliance with the new business tax laws 2025 and help you maximize savings.

Need Working Capital? Get a Small Business Loan from Money Man 4 Business

Navigating tax laws and optimizing deductions is essential for any business, but having access to working capital can be just as crucial. If you’re looking for flexible business financing, Money Man 4 Business offers tailored loan solutions to help you manage your cash flow, expand operations, or invest in new opportunities.

Why Choose Money Man 4 Business?

✅ Fast approvals for business loans & working capital ✅ Competitive interest rates ✅ Funding options from $10,000 to $1,000,000+ ✅ No collateral required for most loans

Whether you need funds to cover tax payments, purchase equipment, or manage daily expenses, our small business loans can help you stay ahead.

📌 Get started today! Visit Money Man 4 Business or call us for a personalized consultation.


Final Thoughts on Business Tax Laws 2025

Staying informed about new business tax laws in 2025 and implementing effective tax strategies can help your business save thousands of dollars. Whether you’re a small business owner, a freelancer, or a corporation, there are many legal ways to reduce your tax burden while remaining compliant with IRS regulations.

By taking proactive steps now, you can maximize tax benefits and set your business up for financial success in 2025 and beyond.

📌 Need help with tax planning? Consult a CPA or tax professional to explore the best tax-saving options for your business!